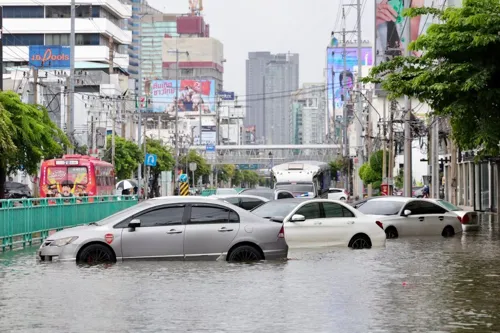
An actuarial lecturer argues that flood risk for a business is less about damaged assets and more about how long revenue stops while rent, wages and loan repayments continue. Practical steps: list which suppliers, roads, systems and key customers you depend on, and check whether a backup exists outside the same flood zone. Find single points of failure, such as one machine with a long parts lead time. Simulate how long your cash lasts if sales stop suddenly, separating deferred sales from lost sales and listing new costs like temporary premises and repairs. Set who acts when a heavy-rain warning is issued, before the event happens.
← Back to all articles