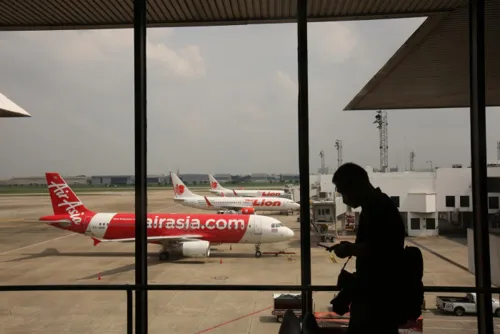
Thailand's low-cost carrier sector is mature and dominated by foreign airlines (AirAsia, Lion Air, Vietjet). Analysts argue that developing a new Thai domestic LCC is no longer feasible due to intense competition and the high barriers to entry—capital burn, volatile fuel costs, and tourism volatility are punishing. Government support (financing, route guarantees) has been critical for incumbent carriers but is absent for new entrants. Thai investors with capital prefer lower-risk sectors like hospitality and real estate.
← Back to all articles